Meet our attorney

Read our blog

Get in touch today

Counselor. Advisor. Committed To Your Business.

At the SJS Law Firm, we are committed to the success of you and your organization.


Providing individualized service that is tailored to the unique needs of you and your business, we provide the legal support you need to move forward with confidence, secure in the knowledge that you have a legal team watching out for your best interests.


Serving small business owners, entrepreneurs and non-profits, we are here to assist you in all legal aspects of your venture.

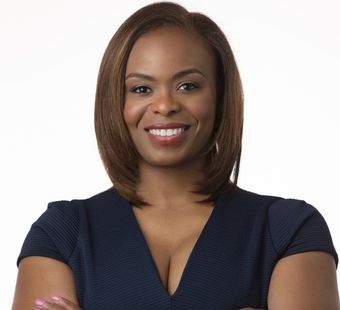
Shavon J. Smith

Our Mission Is To Partner With Clients As Part Of Their Team To Help Them Achieve The Business Of Their Dreams And Plans With Timely And Strategic Legal Advice

Our firm works with clients throughout Washington DC, Prince George’s County, Maryland and the surrounding areas. We offer a range of cost-effective services designed to address all facets of your business, including entity formation, employment matters, contracts, intellectual property, compliance and legal strategy. Our job is to protect you and help you plan for the future by spotting emerging legal trends, allowing you to focus on running and growing your business.


We care about the overall trajectory of your business, not just the legal issues we are called on to solve. We will work closely with you to understand your business and your goals, and customize our services to help you achieve those goals. By delivering creative and proactive solutions and making complicated legal issues easy to understand, we ensure that you have the information and tools you need to be as effective as you can be.

Please contact our firm to discuss your business legal needs. We look forward to helping you build a strong, profitable enterprise.

washington dc

Recent Blog Posts

By Shavon Smith • October 22, 2026
AI can generate a contract in seconds. Making sure it is accurate, complete, and legally sound is another matter. This article explains why AI-generated contracts still require careful legal review and how providing your lawyer with the facts and details of your transaction upfront can help control legal costs. 1. A POLISHED CONTRACT CAN STILL BE WRONG Artificial intelligence offers an appealing way for business owners to save time and control costs. AI can quickly produce what looks like a professional contract or business agreement. But AI-generated contracts can create a growing problem: business owners send them to their lawyers expecting to save on legal fees, only to discover that reviewing and correcting them can take as much time as preparing them from scratch—sometimes more. AI can produce convincing language while omitting critical terms, making unsupported assumptions, or overlooking important details about the transaction. Often, the problem starts with the prompt. If the instructions leave out important details about the parties, their expectations, or the terms of the deal, the resulting contract may look finished but be incomplete or fundamentally flawed. 2. WHY LEGAL REVIEW OF AI-GENERATED CONTRACTS TAKES TIME When a lawyer receives an AI-generated contract, the document must be evaluated for substance, not just grammar and formatting. That means identifying missing terms, checking for inconsistencies, assessing risks, and determining whether the agreement accurately reflects the parties’ intentions. Sometimes, rewriting the contract from scratch is more efficient than fixing the draft. That is not just proofreading; it is substantive legal work which takes time and is billable. Reviewing a flawed draft is not necessarily cheaper than preparing the contract properly in the first place. A lawyer’s ethical and professional obligations do not disappear because AI prepared the first draft. The lawyer remains responsible for independently reviewing the contract, verifying its accuracy, identifying potential legal issues, and ensuring that its terms protect the client’s interests. AI cannot replace the professional judgment, competence, and diligence required to provide legal services. 3. WHAT ACTUALLY HELPS YOUR LAWYER? THE FACTS. AI can be a useful starting point for a contract, but your lawyer needs to understand the underlying transaction to determine what the contract needs to accomplish, whether or not AI has been used to prepare a draft. What is being bought or sold? What have the parties agreed to? What are the payment terms, deadlines, and potential risks? Share the relevant facts, communications, and business objectives. If you are unsure how to address a particular concern or what terms to include, talk it through with your lawyer. A lawyer can explain common approaches, recommend standard clauses, and help determine what makes sense for your transaction. Providing this context upfront helps your lawyer draft or revise a contract that reflects your intentions, protects your interests, and minimizes time spent correcting assumptions or filling gaps. 4. AI CAN HELP. THE FACTS MAKE THE DIFFERENCE. AI can be a useful tool for organizing information, outlining business terms, or identifying questions to discuss with your lawyer. But an AI-generated contract is only as useful as the information and instructions behind it. You do not need a complete contract before contacting your lawyer. Sharing the details of your transaction, business objectives, and any agreed-upon terms with your lawyer is often a more efficient starting point than spending hours trying to generate a contract using AI. Involving your lawyer early helps ensure the agreement reflects your intentions, protects your interests, and avoids unnecessary revisions and legal costs. The SJS Law Firm can help your small business draft, review, and strengthen its contracts to protect your interests and reduce the risk of costly disputes. For a complimentary consultation, please contact us at (202) 505-5309.
By Shavon Smith • September 14, 2026
Contracts underpin nearly every significant business relationship. They allocate risk, define performance obligations, establish payment and termination rights, and provide a framework for resolving disputes. Yet a signed document is not necessarily a well-constructed or enforceable agreement. Today’s lesson tackles the parts of a contract that makes it enforceable. The Lesson: A Contract Is More Than a Signature Contract enforceability varies depending on the circumstances, the type of agreement, and the law that applies. However, an enforceable contract generally requires a clear offer, acceptance, consideration, intent to be legally bound, legal capacity, and a lawful purpose. Some agreements must also be in writing or include specific terms. Note that fraud, mistake, duress, unfair terms, lack of authority, or ambiguity may still affect enforceability. 1. Offer and Acceptance. One party generally makes a clear offer—stating what they are willing to do and on what terms—and the other accepts. The agreement may be written or oral, as long as both parties clearly intend to accept the same terms. A common misconception is that an agreement must be signed to be enforceable. In many circumstances, an oral agreement can be a binding contract. The bigger problem is often proving what the parties actually agreed to, particularly when important terms were discussed but never documented. Some types of agreements, however, are subject to laws requiring a writing, such as certain agreements involving the sale or transfer of real estate or agreements that cannot be performed within one year. Problems can arise when negotiations are incomplete or the parties understand the agreement differently. Emails, texts, proposals, purchase orders, and conversations may become important evidence. For this reason, even when an oral agreement may be legally sufficient, putting the agreement in writing is generally the better business practice. This is why it’s important to memorialize the final terms in one place and make clear which version controls. 2. Consideration. Generally, each party must give or promise something of legal value, often called “consideration.” In a typical business transaction, this is straightforward: one party provides goods or services, and the other provides payment. Consideration can also include a promise to perform a service, deliver property, refrain from taking a particular action, or assume a legal obligation. A promise without the necessary exchange of value may not be enforceable as a contract, although the exchange does not always have to be equal in economic value. 3. Clear, Definite Terms. A contract should be specific enough that the parties (and a court, if necessary), can determine what each party was supposed to do. For a small business, that may include: (a) what products or services are being provided; (b) the scope of the work; (c) price and payment terms; (d) deadlines and delivery dates; (e) each party's responsibilities; (f) change order processes; (g) how and when the relationship can end. The more important the term, the less you should leave it to assumption. 4. Authority, Legality, and Capacity. The person signing an agreement must have authority to bind the business, and the parties must be legally able to understand and agree to its terms. This is especially important for businesses with multiple owners, managers, or employees negotiating with customers and vendors. Contracts also cannot require illegal acts and may need specific terms, disclosures, or a written format depending on the transaction. Your Take-Home Assignment Before signing a contract, take a moment to confirm at least: the parties’ legal names and contact details; the type of goods and/or services provided each party’s responsibilities, including for approvals, materials, and delays; pricing, payment terms, expenses, and late fees; procedures for making changes, deadlines, and renewal and termination terms; dispute resolution; the signer’s authority to bind the business The SJS Law Firm can help your small business draft, review, and strengthen its contracts to protect your interests and reduce the risk of costly disputes. For a complimentary consultation, please contact us at (202) 505-5309.
By Shavon Smith • August 14, 2026
As summer winds down and businesses begin preparing for the busy fall season, August is a good time to think beyond day-to-day operations and consider your long-term business plans. One important, but often overlooked, aspect of planning is business succession. Business succession planning is not just for owners preparing to retire. It is the process of planning for events that could affect the future of your business, including an owner’s retirement, disability, death, bankruptcy, or decision to leave the company. Without a plan in place, these situations can create uncertainty, disrupt operations, and lead to disputes among owners, employees, or family members at a time when stability is most important. For businesses with multiple owners, succession planning often begins with reviewing the company’s governing documents. Many LLC Operating Agreements and corporate bylaws contain provisions addressing ownership transfers and business continuity. These provisions may establish whether the remaining owners have the right to purchase a departing owner’s interest, how that interest will be valued, and the terms under which the purchase will occur. In some cases, businesses choose to memorialize these terms in a separate Buy-Sell Agreement. A Buy-Sell Agreement provides a clear roadmap for ownership transitions by addressing issues such as triggering events, valuation methods, payment terms, and restrictions on transferring ownership interests to third parties. Whether these provisions are incorporated into an Operating Agreement or contained in a standalone Buy-Sell Agreement, having a clear plan in place can help preserve business continuity and reduce the likelihood of costly disputes. Whether your succession provisions are contained in an Operating Agreement or a standalone Buy-Sell Agreement, they should be reviewed periodically—not just when a problem arises. The following questions can help you assess whether your current documents provide the clarity and protection your business needs for a future transition. Questions to Consider: Have you reviewed your Operating Agreement, Bylaws, or other governing documents to ensure they address what happens if an owner becomes disabled, passes away, retires, or can no longer manage the business? If your business has multiple owners, do your governing documents include buy-sell provisions or is there a separate Buy-Sell Agreement addressing ownership transfers? If you are a sole owner of an LLC or corporation, have you established a plan for who will manage the business and how ownership will transfer if you are no longer able to operate it? Have you reviewed whether your ownership records, corporate records, and governing documents accurately reflect your current business structure and succession goals? Have you considered how key business assets—including contracts, intellectual property, customer relationships, and other valuable assets—will be handled during a transition in ownership or management? The SJS Law Firm can help your small business plan and draft succession documents to protect your business. For a complimentary consultation, please get in touch with us at (202) 505-5309.